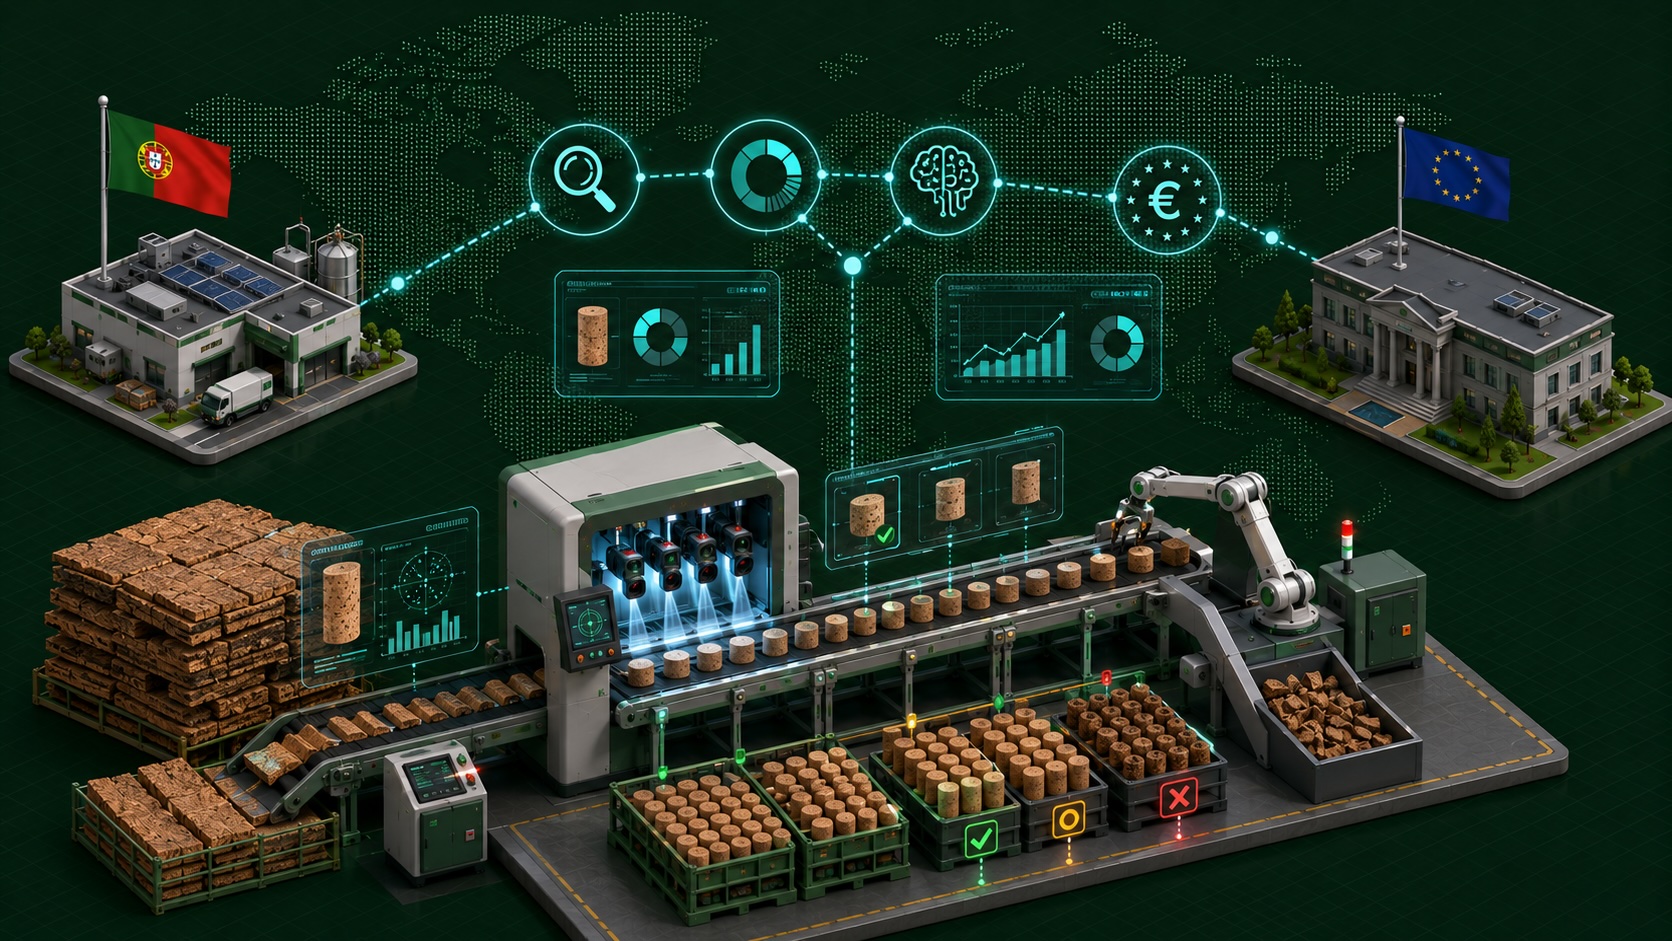
Portugal produces roughly half the world’s cork, and after a century of grading stoppers by hand, the sector is moving to AI-powered vision inspection. The large groups have already made the switch; only around 8% of Portuguese SMEs have adopted AI tools at all. With equipment prices falling and Portugal 2030 and PRR co-financing reaching 50–75%, the gap between the two speeds of this industry is being decided right now.
Portugal’s cork industry, the world’s largest, built on roughly half of global cork production and centred on the Aveiro-Porto cluster, is in the middle of a quiet technological shift. After more than a century of relying on skilled human inspectors to sort cork by hand, the sector is moving toward AI-powered vision systems for quality grading, alongside broader automation of handling and packaging. For a sector currently navigating a cyclical downturn in raw material trade and margin pressure, this shift is arriving at a genuinely useful moment — but it is not arriving evenly across the industry.
Why Cork Quality Control Is Uniquely Hard to Automate, and Why It’s Happening Anyway
Grading a cork stopper is a subtler task than it might appear. Natural cork is a biological material, and every stopper varies in porosity, density, and surface defects in ways that used to require years of hands-on training to judge reliably. That is precisely why automated visual classification of cork has become an active research field. A recent systematic academic review identified over fifty published studies on automated cork quality classification methods, spanning classical image processing, machine learning, and deep learning approaches — evidence that this is now a mature technical domain, not an experimental one.
Some of the sector’s largest players are already deploying this technology at scale, and doing so publicly. Corticeira Amorim, the global leader, has described integrating AI transversally across its operations, including cork selection itself. Other established names in the sector have built proprietary high-precision inspection systems combining advanced imaging with AI-based defect detection, reporting accuracy rates in the high 90s of a percent and citing measurable reductions in non-value-added labour. Portuguese business press has begun explicitly framing the sector as becoming high-tech — a notable shift in language for an industry historically associated with artisanal, hand-based craft.
The Gap: A Leaders’ Story So Far, Not a Sector-Wide One
Here is the part of the picture that matters more for the industry’s medium-term competitiveness. What is publicly documented is concentrated among a small number of large, well-capitalised groups with in-house R&D capacity to build or commission bespoke inspection systems. Portugal’s cork sector, like most of Portugal’s manufacturing base, is structured as a small number of large groups surrounded by a much longer tail of small and mid-sized producers, many family-owned, clustered around Aveiro and Santa Maria da Feira.
This pattern is consistent with a broader, well-documented gap in Portuguese SME technology adoption. Recent national data shows only around 8% of Portuguese SMEs have adopted AI tools, with just over half reaching even a basic level of digital maturity. There is no reason to assume cork-sector SMEs sit meaningfully above that national average. If anything, a sector currently absorbing falling raw-material trade volumes and margin compression is a plausible candidate for being at or below it, simply because capital is tighter precisely when the case for investment is strongest.
This creates a real strategic risk worth naming plainly. If AI-driven quality grading and yield optimisation become a genuine competitive differentiator — through better grading consistency, higher usable-stopper yield per cork plank, and lower dependence on scarce experienced sorters — then a two-speed industry could emerge, where a handful of large groups pull further ahead on cost and consistency while a large number of smaller producers compete on legacy processes alone.
Why the Cost Barrier May Be More Solvable Than It Looks
The capital cost argument against automation for smaller cork producers is real but incomplete, for two reasons that are often considered separately rather than together.
The equipment cost itself has changed. Industrial vision-inspection and AI-based sorting technology, historically the domain of a handful of specialised European and Japanese suppliers building custom systems at premium prices, is now available at meaningfully lower price points from a broader base of international manufacturers with established food, beverage, and general industrial inspection product lines — categories with genuine technical overlap with cork sorting, such as defect detection, surface classification, and high-speed optical inspection. This does not mean any inspection system is a drop-in fit for cork specifically. Cork’s material variability requires proper calibration and validation regardless of the hardware source. But it does mean the entry price point for this category of technology is no longer automatically out of reach for a mid-sized producer the way a fully bespoke system might be.
Less widely discussed, Portugal currently has an unusually favourable public funding environment for exactly this kind of investment. Through Portugal 2030 and the Recovery and Resilience Plan (PRR), SMEs can currently access non-reimbursable grants covering a significant share of digital transformation and automation investment, with published co-financing rates reaching as high as 50 to 75% in some programmes and regions, alongside smaller, faster diagnostic vouchers designed specifically to help a company scope an initial Industry 4.0 roadmap before committing to larger capital spend.
Put together, a mid-sized cork producer evaluating AI-based sorting today is not necessarily choosing between an expensive bespoke system and no automation at all. A lower entry-cost equipment option combined with available co-financing can change the net capital outlay substantially. Whether that combination makes sense for a specific producer depends heavily on its scale, product mix, and current defect and yield economics. This is a due-diligence question for each company, not a blanket recommendation.
What This Means in Practice
For cork producers themselves, the practical takeaway is that the assumption that automation is only for the big groups is worth re-testing now, specifically because the two obstacles that historically made it true — high equipment cost and no funding support — have both shifted in the past year. A sensible first step, consistent with how the sector’s own technical literature frames it, is not to attempt full production-line automation at once, but to start narrowly: install inspection and yield-tracking instrumentation at the specific bottleneck causing the most waste or rework today, use that data to build a concrete business case, and scale from there.
For buyers and partners working with Portuguese cork suppliers — including wine, spirits, and increasingly construction, marine, and design-sector clients — this technology shift is also a useful diligence question to start asking directly. How is quality consistency being maintained as raw material costs and availability continue to fluctuate, and is a given supplier’s quality control process still primarily manual or increasingly instrumented? The answer is likely to vary considerably across the industry’s supplier base for the next several years, and that variation is itself useful information for a sourcing decision.
A Practical Framework for Buyers and Producers
For a European buyer or a cork producer assessing where a given supplier or facility sits on this spectrum, a few concrete checkpoints are worth building into evaluation now.
Ask directly whether grading is manual, hybrid, or instrumented. A supplier’s answer, and how specific it is, is itself informative. A precise description of an inspection system and its accuracy rate signals a different level of maturity than a general reassurance about quality standards.
Request defect and yield data over time, not just a current quality certificate. Instrumented grading systems generate the kind of consistent, comparable data that manual grading typically cannot produce at the same granularity. A supplier able to share yield trends is more likely to have moved past purely manual processes.
For producers, size the first investment to the worst bottleneck, not the whole line. The academic and industry literature on cork inspection technology consistently points toward targeted, incremental adoption rather than a single large capital project, which also makes the co-financing case easier to build and justify internally.
Treat Portugal 2030 and PRR funding windows as time-sensitive, not permanent. Co-financing rates and voucher programmes tied to EU recovery funding operate on defined timelines. A producer evaluating automation should confirm current eligibility and deadlines rather than assuming favourable terms will remain available indefinitely.
For buyers, factor supplier technology maturity into long-term sourcing risk, not just current pricing. A supplier still reliant entirely on manual grading may face rising cost and consistency pressure relative to instrumented competitors over the next several years, which is relevant to the durability of a sourcing relationship, not only its current terms.
The Honest Caveats
A balanced assessment needs to include what remains uncertain.
Company-specific technology adoption status for smaller and mid-sized producers was not independently verifiable from public sources. The observations in this article describe sector-level patterns, drawn from national SME digitalisation data and the visible practices of large groups, not individual company assessments. A specific supplier’s actual grading process should be confirmed directly rather than inferred from sector-wide statistics.
Accuracy figures cited by individual companies (accuracy rates in the high 90s of a percent) are self-reported. These are useful signals of technical capability but have not been independently audited for this article, and methodology can vary meaningfully between systems and vendors.
Co-financing rates and programme details for Portugal 2030 and the PRR are subject to change. The 50 to 75% range cited reflects published rates in some programmes and regions as of 2026, not a guaranteed rate applicable to every producer or investment category. Current terms should be confirmed directly with the relevant national agency before being used in an investment decision.
The Takeaway
Portugal’s cork industry is not choosing between tradition and technology. Its largest players have already answered that question. The more consequential question for the industry’s next five years is whether the technological gap between leaders and the broader supplier base widens or narrows — and that will likely be decided less by the existence of the technology itself than by which producers manage to combine falling equipment costs with the public co-financing currently available to close that gap while it still exists.
Tags
Sources
portugalglobal.pt / AICEP (Amorim AI integration, March 2026); The Portugal News (cork industry digitalisation, March 2026); academic systematic review of automated cork classification methods (Coimbra CISUC, February 2026); The Drinks Business (cork sector automation and inspection technologies, 2025); PME Incentivos and Estrategor (Portugal 2030 / PRR digital transformation funding, 2026); industry directories (europages, bizfeira) for sector structure context. Company-specific technology adoption status for smaller and mid-sized producers was not independently verifiable from public sources and is not asserted in this article; the observations above describe sector-level patterns, not individual company assessments.